
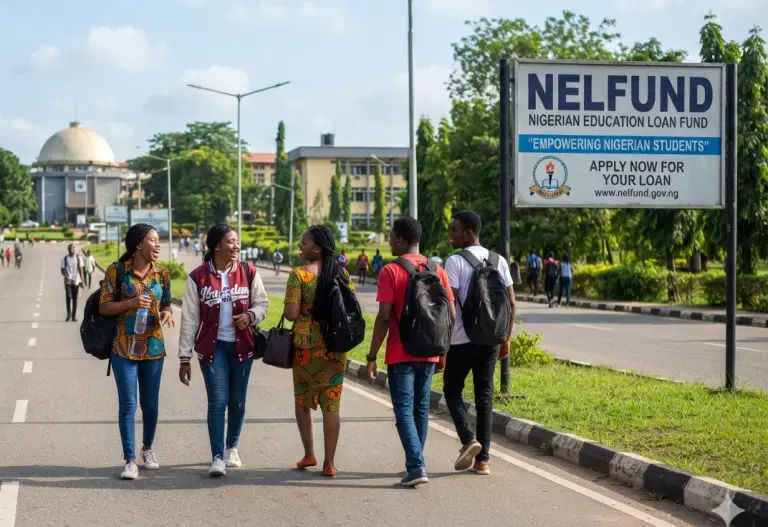
NELFUND: Student Loan Repayment Capped at 10% of Graduates’ Gross Income
Graduates who benefited from the Nigerian Education Loan Fund (NELFUND) will not be required to repay more than 10 per cent of their gross monthly income under the Students Loans (Access to Higher Education) Act, 2024.
The provision is designed to prevent beneficiaries from facing excessive financial pressure while repaying loans obtained to finance their higher education, vocational training and skills acquisition.
Under the law, beneficiaries are expected to begin repayment after completing their studies and securing employment. However, the monthly deduction cannot exceed 10 per cent of their gross income until the outstanding loan and applicable charges are fully repaid.
The Act also provides a transition period for beneficiaries, stipulating that NELFUND cannot commence enforcement action until two years after the beneficiary completes the National Youth Service Corps (NYSC) programme or obtains an exemption from the scheme.
Room for repayment extension
Beneficiaries who remain unemployed or have no income may apply to NELFUND for an extension by submitting a sworn statement in the manner prescribed by the Fund.
The repayment framework comes as the student loan scheme continues to expand. NELFUND disclosed that, as of July 3, 2026, it had processed 1,635,676 applications and recorded approximately 850,000 unique beneficiaries.
The Fund has also disbursed N303.9 billion to beneficiaries, comprising N190 billion for institutional charges and N113.8 billion in upkeep support for eligible students.
The distinction between applications processed and unique beneficiaries is important, as some students have submitted more than one application. Consequently, the approximately 850,000 unique beneficiaries represent individual students who have benefited from the scheme.
The repayment mechanism is central to the long-term sustainability of NELFUND, which is expected to recover loans from beneficiaries and use the funds to support future applicants.
Under the 2024 Act, NELFUND is empowered to establish and maintain a diversified pool of funds for providing loans to qualified applicants, as well as recover debts owed to it through lawful means, including debt recovery proceedings.
Employer’s role in loan recovery
The legislation also places responsibilities on employers in the recovery process.
Every prospective employer is required to make enquiries from NELFUND about the student-loan status of prospective employees. Where an employer is informed that an employee is a beneficiary who has not completed repayment, the employer is expected to provide information required by NELFUND to facilitate recovery of the outstanding loan and applicable charges.
Employers who contravene the provision may face sanctions, including a fine of at least N2 million, imprisonment for a minimum of one year, or both.
The income-based repayment structure means that beneficiaries earning higher salaries would make larger monthly repayments, while those earning lower incomes would make proportionately smaller payments.
For instance, a graduate earning a gross monthly income of N200,000 would have a maximum monthly repayment obligation of N20,000, while a beneficiary earning N500,000 would have a maximum monthly repayment of N50,000 under the 10 per cent ceiling.
The law does not, however, impose a fixed monthly repayment amount. Rather, the maximum deduction is tied directly to the beneficiary’s gross income.
NELFUND’s repayment obligation begins after graduation and employment, although beneficiaries are allowed to voluntarily commence repayment before completing their studies.
The legislation also provides protection for beneficiaries who are unable to secure employment. Such beneficiaries may seek an extension from NELFUND by submitting a sworn statement in accordance with the procedure prescribed by the Board.
Penalties for false claims
The Act provides sanctions for beneficiaries who submit false statements to NELFUND. A person convicted of making a false declaration may face imprisonment for up to three years.
The repayment framework is part of a broader financing structure under which NELFUND is expected to operate as a revolving education financing institution rather than merely as a conventional government grant programme.
Under the Act, NELFUND’s General Reserve Fund is expected to receive funding from various sources, including one per cent of taxes, levies and duties collected by the Federal Inland Revenue Service (FIRS) accruing to the Federal Government, appropriations by the National Assembly, loan repayments, investment income, government funding, proceeds from education bonds and other debt instruments, donations, grants and endowments.
The Fund is authorised to use its resources to provide loans to qualified applicants for tuition, fees, institutional charges and upkeep, in addition to approved operational expenses.
The Act also requires NELFUND to maintain proper accounts and records, with its accounts audited annually by an independent firm of auditors.
The Fund is further required to publish its annual report within six months after the end of each financial year and submit its audited accounts to the President and the National Assembly.
With about 850,000 beneficiaries and N303.9 billion already disbursed, the effectiveness of the repayment system is expected to play an increasingly important role in determining the future sustainability of the student loan scheme.
The Fund’s capacity to finance additional students will depend not only on fresh government and other funding sources but also, over time, on its ability to recover loans from beneficiaries who have graduated and secured employment.
The 2024 Act therefore seeks to strike a balance between expanding access to higher education and ensuring responsible loan recovery by giving beneficiaries access to financing while preventing repayment from becoming an immediate or excessive burden after graduation.
For beneficiaries, the 10 per cent ceiling provides a statutory limit on how much of their gross monthly income can be deducted.
For NELFUND, however, the major challenge will be developing an effective system for tracking beneficiaries after graduation, identifying those who secure employment, collecting repayments and recycling recovered funds into new student loans.
As the scheme expands, the success of that recovery mechanism could determine whether NELFUND becomes a sustainable revolving fund capable of financing successive generations of Nigerian students or remains significantly dependent on fresh government allocations.
How to apply for NELFUND student loan
Prospective beneficiaries can apply for the NELFUND student loan through the Fund’s official portal.
Registration and verification
- Visit the NELFUND application portal and select “Apply Now.”
- Provide your National Identification Number (NIN) and JAMB registration number.
- Select your public tertiary institution, enter your matriculation number and verify your date of birth.
- Provide your email address, create a secure password and complete the email verification process.
Completing your profile
After creating an account, applicants should log in and provide their current phone number and residential address.
Applicants are also required to provide their Bank Verification Number (BVN) and eligible commercial bank account details before proceeding with the loan application.
Applicants should carefully review and save their profile information before requesting the loan.
Submitting the loan application
Applicants should select “Request for Student Loan” and choose the relevant loan option.
Institutional charges should be selected first, while applicants seeking upkeep support should also apply for the institutional charges component as required under the scheme.
Applicants should upload the required documents, such as their admission letter, review the information provided, accept the declaration and terms and conditions, and submit the application.